Serving on a Homeowners Association (HOA) board is a demanding volunteer role, requiring dedication to maintaining community standards and property values. However, this responsibility also carries significant personal risk, exposing members to potential lawsuits.
In today’s complex environment – shaped by economic pressures, increased litigation, and the ongoing effects of tragic events – securing robust HOA D&O insurance is not just prudent; it’s an absolute necessity to mitigate HOA board member liability.
Understanding the Basics: What is Directors and Officers Insurance for HOA?
Directors and Officers (D&O) insurance protects the personal assets of HOA board members, and often committee members, volunteers, and employees, if they are sued for alleged wrongful acts performed in their official capacities.
These “wrongful acts” encompass a wide range, including breach of fiduciary duty (a frequent claim), negligence, errors, failure to comply with governing documents or laws, discrimination, and mismanagement.
Directors and Officers insurance for HOA typically covers legal defense costs, settlements, and judgments up to the policy limits, shielding board members from devastating personal financial loss. It’s crucial to distinguish this from general liability insurance, which covers bodily injury and property damage claims.
Why the Stakes Are Higher Than Ever: Liability in a Challenging Climate
The environment for HOA boards has become significantly more challenging recently:
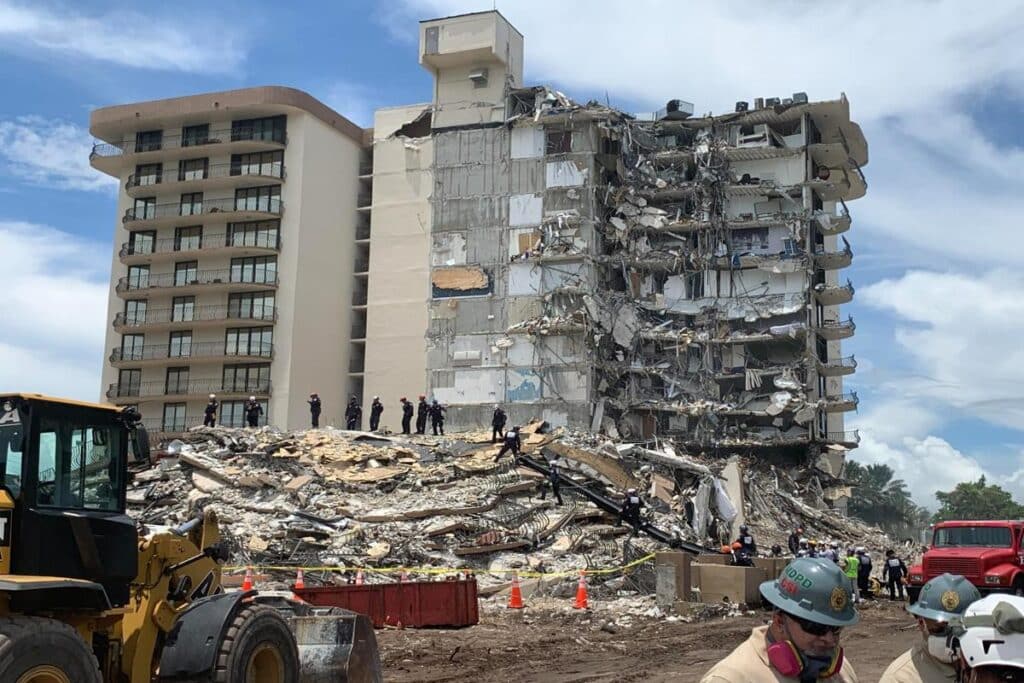
- The Shadow of Surfside: The tragic Champlain Towers South collapse in 2021 dramatically highlighted the potential consequences of deferred maintenance and board decisions. Subsequent legislation, like Florida’s SB 4-D requiring stricter inspections and mandatory reserve funding, has increased financial pressure and scrutiny on boards.
- The Broader HOA Insurance Crisis: Beyond D&O, HOAs are grappling with an HOA insurance crisis, particularly concerning property insurance. Skyrocketing premiums (sometimes doubling or more), reduced coverage availability, and insurers exiting markets in high-risk areas (like Florida and California) are straining budgets. This crisis is fueled by increased natural disasters and rising construction costs.
- Economic Pressures & Difficult Choices: Inflation adds another layer of difficulty, increasing costs for everything from landscaping to repairs. These financial strains force boards into tough decisions like raising dues, levying special assessments, cutting services, or delaying maintenance – actions that can easily trigger homeowner lawsuits alleging mismanagement or breach of fiduciary duty, amplifying HOA board member liability.
The 4 Vital Checks for Your HOA D&O Insurance
In this high-risk climate, a basic or add-on D&O policy is often insufficient. Effective HOA risk management demands a thorough evaluation of your coverage. Here are four vital checks every board must perform:
- Assess Policy Limits: Are your coverage limits high enough? Legal defense costs and potential judgments can escalate quickly. Ensure limits reflect the current litigious environment and the potential scale of claims against your specific HOA.
- Scrutinize Exclusions: Understand precisely what your policy doesn’t cover. Common exclusions can include claims related to fraud, known violations of laws or governing documents, prior or pending litigation, or sometimes non-monetary relief (like disputes over rule enforcement or aesthetics).
- Verify Coverage Breadth: Confirm the policy protects past, present, and future directors and officers, as well as committee members, volunteers, and potentially employees or property managers. Check if it covers claims seeking both monetary damages and non-monetary relief.
- Consult an Expert: Navigating HOA D&O insurance complexities requires specialized knowledge. Work with an insurance broker experienced in community associations to ensure your policy is comprehensive and tailored to your HOA’s specific risks. This is a key part of sound HOA risk management.
Beyond Protection: Securing Your Community’s Future
Strong HOA D&O insurance offers benefits beyond safeguarding individual board members’ assets. It provides financial stability for the entire HOA by covering potentially crippling legal defense costs.
Furthermore, robust protection helps attract and retain qualified, dedicated volunteers willing to serve, knowing they won’t face personal financial ruin for their service.
Prioritizing comprehensive Directors and Officers insurance for HOA is fundamental to responsible governance, protecting both the leaders and the community they serve.
Ensure Your Coverage Delivers: Get a Free Expert Review
Buying insurance without verifying that its terms are as broad and responsive as you expect is like scoring an own-goal – relying on an unverified policy is a significant gamble. Are you certain your HOA D&O insurance provides the protection you expect?
Don’t wait for a crisis to uncover costly gaps. It’s a no-brainer to leverage PlausTech’s CoverageLocator, powered by our proprietary CoverageXpert database, for a free policy review.
This expert analysis ensures your policy aligns with the vital checks discussed and confirms your protection will truly deliver when you need it most.
Secure peace of mind for your board and community – contact PlausTech today for your complimentary HOA D&O insurance policy analysis.